
Categories
BuyersPublished November 11, 2026
Credit Scoring Is Changing: What Prescott Homebuyers Should Know
Quick, what credit score do you need to buy a home? If a number pops into your head, it could be off. And the right answer is getting harder to pin down, because the way credit scores are determined and delivered is changing.
If you are thinking about buying in Prescott or the Quad Cities, here is what to know about credit right now.
The Number Is Easy to Guess Wrong
Fannie Mae has surveyed consumers about what it takes to get a mortgage since 2015. In its December 2023 survey, nearly one-third of consumers (32%) either did not know the minimum credit score lenders require or significantly over- or underestimated it.
For reference, Fannie Mae's Selling Guide lists a 620 minimum score for manually underwritten fixed-rate loans. Since November 2025, loans run through Fannie Mae's automated underwriting system no longer have a set minimum score built in, though individual lenders can still set their own requirements. Your lender will tell you what applies to your loan.
Guessing wrong can cost you. A renter who assumes their score is too low to qualify for a mortgage may never take steps to find out for sure.
Credit Rules Are Changing
For decades, loans sold to Fannie Mae and Freddie Mac required scores from one model, Classic FICO. The Federal Housing Finance Agency (FHFA) validated two newer models, VantageScore 4.0 and FICO 10T, to bring more competition to credit scoring. As of FHFA's October 2, 2026 update, lenders can choose between Classic FICO and VantageScore 4.0 for loans sold to Fannie Mae and Freddie Mac. FICO 10T is approved but is not yet eligible for delivery, and no date has been set for it.
A different model can mean a different number for the same person. VantageScore says about 33 million more Americans can be scored by its models. So the score you saw on an app last month may not be the one your lender pulls. Not every lender is set up to use the newer model yet, so ask yours which one they use.
The models may be new, but the basics have not changed.
Do Your Part and Partner With a Pro
Your credit score matters no matter how it is measured. The same basic rules will help your profile in the old and new score models:
- Know your score: check it and keep track of how it changes over time
- Grow your score: pay your bills on time and try to keep your credit balances low
- Protect your score: understand how new credit and loans can affect it
- Talk to a mortgage pro: get current, accurate advice for your situation
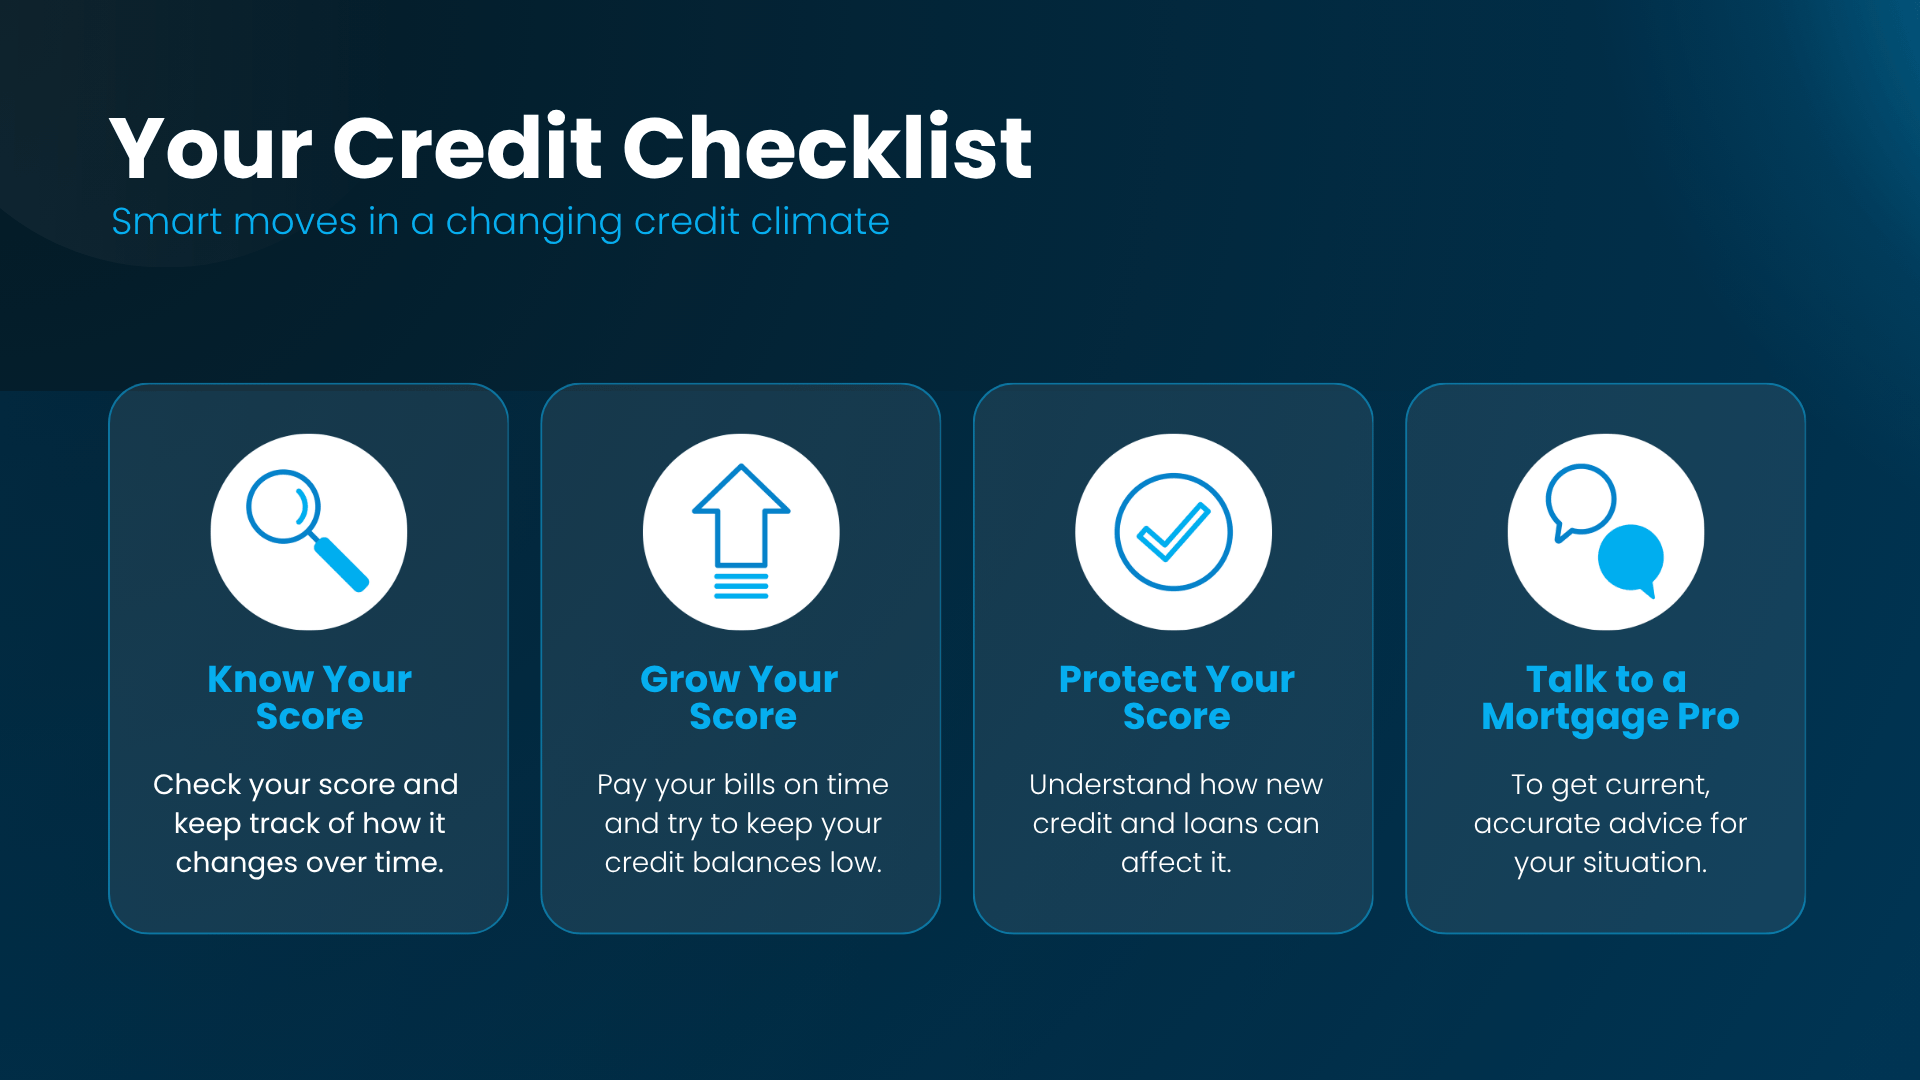
Credit models may change, but the general advice for improving your score does not. Financial awareness and consistency, mixed with a little willpower, can go a long way.
Bottom Line
Do not make credit or homebuying decisions from a chart, an app, or a friend's advice. With the rules shifting and so many misconceptions out there, it is never too early to talk to a professional loan officer about credit, budgeting, and what it would take to qualify for a mortgage.
If you are thinking about a move in Prescott or the Quad Cities, reach out and we can talk through your next steps.
Sources: FHFA credit score policy page (updated Oct. 2, 2026); Fannie Mae Selling Guide, credit scores; Fannie Mae Consumer Mortgage Understanding Study (2023); VantageScore; Original article.
Jen Bergamini
Director of Ops | The Bergamini Group | Keller Williams Arizona Realty | PLACE
or another way