
Categories
BuyersPublished September 28, 2026
The Mortgage Rate You See Online Isn't Necessarily the One You'd Get
If you have been keeping an eye on financial headlines lately, you might have noticed reports that mortgage rates have
national advertised average is rarely the exact rate you'll secure.
It is a common misunderstanding that national rate headlines apply across the board to every homebuyer. In reality,
What Actually Shapes Your Personal Mortgage Rate?
Advertised promotional rates and your custom home loan quote are two very different things. National media outlets publish generic estimates that cannot account for your specific financial goals or local Quad-Cities market conditions.
To determine your true borrowing cost, a local lender will evaluate several key factors:
- Your credit score: Lenders closely review your credit history, including payment consistency, credit utilization, and credit account longevity. Buyers with an exceptional
credit score - Your debt-to-income (DTI) ratio: This metric compares your total monthly debt payments against your gross monthly income. A lower DTI ratio demonstrates stronger repayment ability, which often results in more favorable rate quotes.
- Down payment amount & Loan-to-Value (LTV): The size of your initial down payment directly impacts your mortgage risk. Your
LTV - Loan structure & term length: Different loan programs—such as conventional, FHA, VA, or USDA financing—come with unique pricing structures. Mortgage rates vary based on whether you select a fixed, adjustable, 15-year, or 30-year option.
Once you find a home you love in Prescott or Yavapai County, a few additional strategies can alter your overall rate and monthly obligation:
- Mortgage rate buydowns: Paying upfront discount points (or securing a temporary rate buydown) reduces your effective interest rate and lowers your monthly payment. In many cases, home sellers or local builders offer buydown credits as an incentive to close.
- Seller concessions: Loan guidelines permit sellers to contribute toward buyer
closing costs
The Best Place to Start? Secure a Local Pre-Approval.
Instead of guessing whether your real financing terms will be
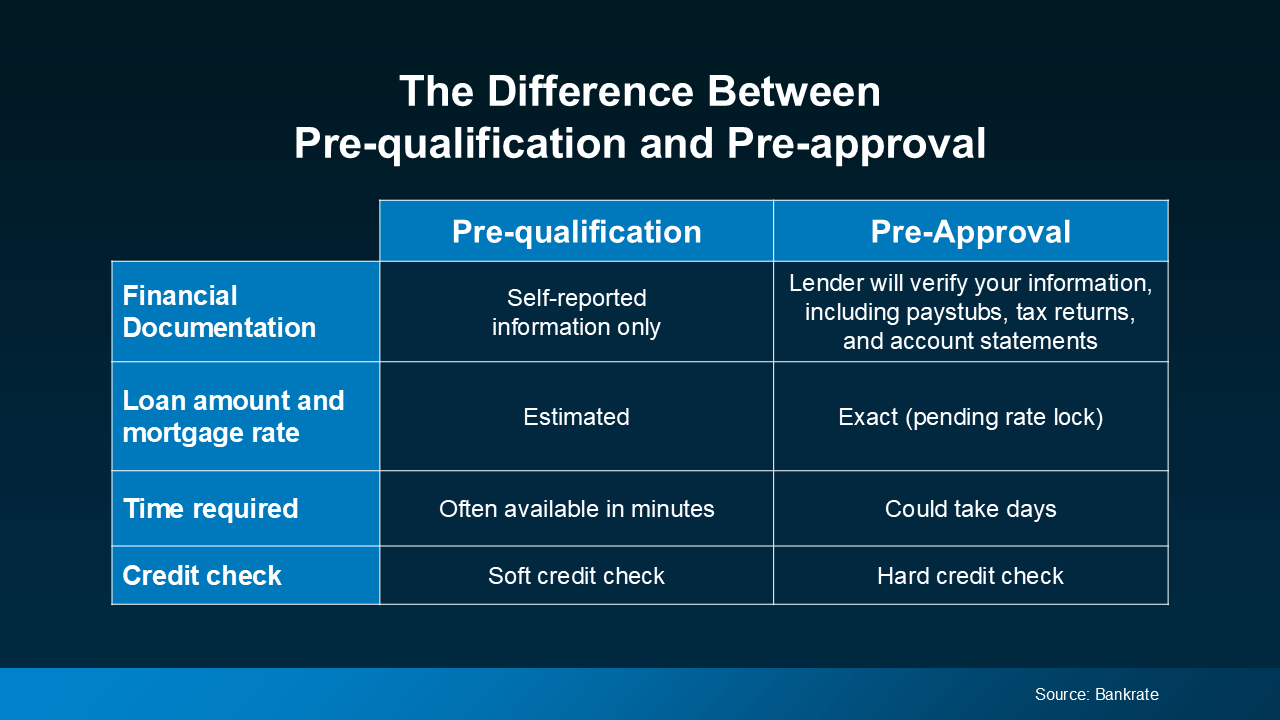
Be sure to ask for a full pre-approval rather than just a pre-qualification:
- Pre-qualification provides a rough estimate based on unverified, self-reported details.
- Pre-approval involves thorough verification of your income and financial documentation, giving you a firm, conditional loan commitment.
A verified pre-approval gives you a clear competitive advantage when submitting offers on Prescott properties.
Just know that, of the two, the pre-approval process gives you a more accurate picture of your options than pre-qualification. Bankrate gives a quick comparison so you can see why:
Bottom Line
Headlines and social media make today’s rates sound high. But remember, the rate you see online and your actual rate could be different. The only way to know what your rate could be is to talk to a trusted lender.
With the right help, you can find out what your real rate is – and where it can take you.
Jen Bergamini
Director of Ops | The Bergamini Group | Keller Williams Arizona Realty | PLACE
or another way